What the Fed’s October 2026 Decision Means for Incline Village Home Buyers and Sellers
Lake Tahoe Cole Mizak November 6, 2026
Lake Tahoe Cole Mizak November 6, 2026
On October 28, 2026, the Federal Reserve held its benchmark rate at 3.75%–4.00%, and markets now lean toward a hike in December, not a cut. National 30-year mortgage rates are sitting near 7%, down slightly from a 7.40% peak in mid-October. For Incline Village, that means buyers who finance have more negotiating room than they’ve had in years, cash buyers hold the strongest hand, and sellers win by pricing to today’s rates rather than waiting for a cut that may not come soon.
The Fed kept the federal funds rate at 3.75%–4.00%, where it has been since a quarter-point hike on September 16. The vote was 10–2, and both dissenters, Governor Lisa Cook and Cleveland Fed President Beth Hammack, wanted another 25-basis-point increase right away.
The Fed’s statement upgraded the economy to “strong” and said plainly that inflation remains elevated. That’s backed by the data: September CPI ran 3.7% year over year, pushed hard by a 20.4% jump in energy prices, and core PCE (the Fed’s preferred gauge) was 3.0% in August.
Chair Kevin Warsh called the meeting a serious, sober discussion. Rate futures took the hint: after the meeting they priced roughly an 85% chance of a quarter-point hike at the December 9 meeting, up from near-certainty of a hold beforehand.
If you’ve been hearing that rate cuts are coming, here’s the reality: the conversation inside the Fed right now is about whether to raise rates again, not lower them.
Mortgage rates follow the 10-year Treasury more closely than the Fed’s own rate, and the 10-year moved up to about 5.04% on decision day. That’s why the 30-year fixed climbed from the 6.7% range in early September to 7.40% on October 8, its highest level since November 2023. As of November 2, Zillow’s average 30-year fixed purchase rate was 7.10%.
Redfin’s chief economist said on October 29 that there are many signs rates will stay higher for longer. Plan around roughly 7% for now, not the 6% many buyers were hoping for.
Most Incline Village purchases need a jumbo loan, since the 2026 baseline conforming limit is $832,750. Jumbo pricing varies a lot by lender and relationship, so here is a simple illustration: a $3 million home with 25% down, a $2.25 million 30-year fixed loan, principal and interest only.
Rate | Monthly P&I | vs. 6.7% |
|---|---|---|
6.70% | $14,519 | — |
7.10% | $15,121 | +$602 |
7.40% | $15,579 | +$1,060 |
The swing from September’s lows to October’s peak works out to more than $12,700 a year on this one loan. Keep in mind that federal mortgage interest deductions are capped at $750,000 of loan principal, so most of the interest on a loan this size isn’t deductible.
Waiting for a rate cut is a bet, not a plan. With the Fed debating a hike, the buyers doing best right now are the ones negotiating on price and terms today, then refinancing if rates fall later.
Sellers who price to today’s 7% reality will sell this winter. Sellers who price for a 6% market that hasn’t arrived will sit.
Fed headlines hit Incline Village differently than they hit a typical suburb. A large share of buyers here pay cash or borrow against portfolios, so a quarter point on the 30-year changes their timing less than it changes their leverage in negotiation.
Three things keep demand steadier here than rates alone would suggest:
Where rates do bite is the financed middle of the market: condos, townhomes and single-family homes under about $3 million. That’s where buyers have the most room and sellers need the sharpest pricing.
Local snapshot: [Insert latest Incline Village MLS figures: median sale price, average days on market, months of inventory and sale-to-list ratio, Q3 or October 2026.]
Two reports will shape December: the October jobs report, out November 6, and the October CPI report, due November 10. Strong numbers make a December hike more likely and push mortgage rates higher. Softer numbers could ease Treasury yields and bring rates back toward the high 6% range.
The Fed’s last meeting of 2026 runs December 8–9, with its decision and updated economic projections on December 9. We’ll update this post as soon as it’s out.
No. On October 28, 2026, the Fed held the federal funds rate at 3.75%–4.00%. Two of the 12 voters wanted to raise rates instead.
Probably not by much in the near term. Markets were pricing a likely December rate hike after the October meeting, and national 30-year rates were about 7.1% in early November.
It can be for buyers with strong financing or cash. Higher rates have reduced competition in parts of the market, which gives buyers more room to negotiate on price, credits and rate buydowns.
Not necessarily. If the Fed raises rates in December, spring buyers may face higher borrowing costs, and winter listings usually face less competition from other sellers.
Less than they affect the rest of the market. Lakefront and trophy properties on the Nevada side are scarce and often bought with cash, so rates move timing and terms more than price.
The 2026 baseline conforming loan limit is $832,750, and any loan above your county’s limit is a jumbo loan. Because most Incline Village homes sell well above that, most financed buyers here use jumbo loans.
Whether you’re buying, selling or deciding between the two, the right strategy depends on your financing, your timeline and your segment of the market. I’ll walk you through current comps, buydown math and the Nevada residency picture for your specific situation.
Call or text 775-225-2549 or email [email protected] to request a private market analysis.
Cole Mizak leads the Mizak Mountain Luxury Team at Compass and is the #1 agent by total transactions in Incline Village in 2026. With more than $285 million in career sales, he ranks in the RealTrends top 1.5% nationally, holds the CRS and CLHMS (Million Dollar Guild) designations and was named to NAR’s 2024 30 Under 30. Licensed in Nevada (S.0179606) and California (DRE 02126888).
This article is for general information and isn’t financial, tax or legal advice. Rates and market conditions change quickly; talk with a lender and a tax professional about your situation.
Stay up to date on the latest real estate trends.
Lake Tahoe
November 6, 2026
Rates held at 3.75%–4.00% and a December hike is on the table. Here’s how to buy or sell in Incline Village with mortgage rates near 7%.
Lake Tahoe
November 4, 2026
Nevada has a new governor, Congress changed hands and California voted on taxing the wealthy. Here’s what actually changes for Incline Village buyers and sellers.
Lake Tahoe
October 7, 2026
Closed sales, Incline Village only, one agent: $68M+ year to date as of 10/07/2026 from MLS data.
Lake Tahoe
October 6, 2026
The June 4, 1968 boundary rule, 2026-27 IVGID fees, and how to verify a property before you write an offer.
Lake Tahoe
September 30, 2026
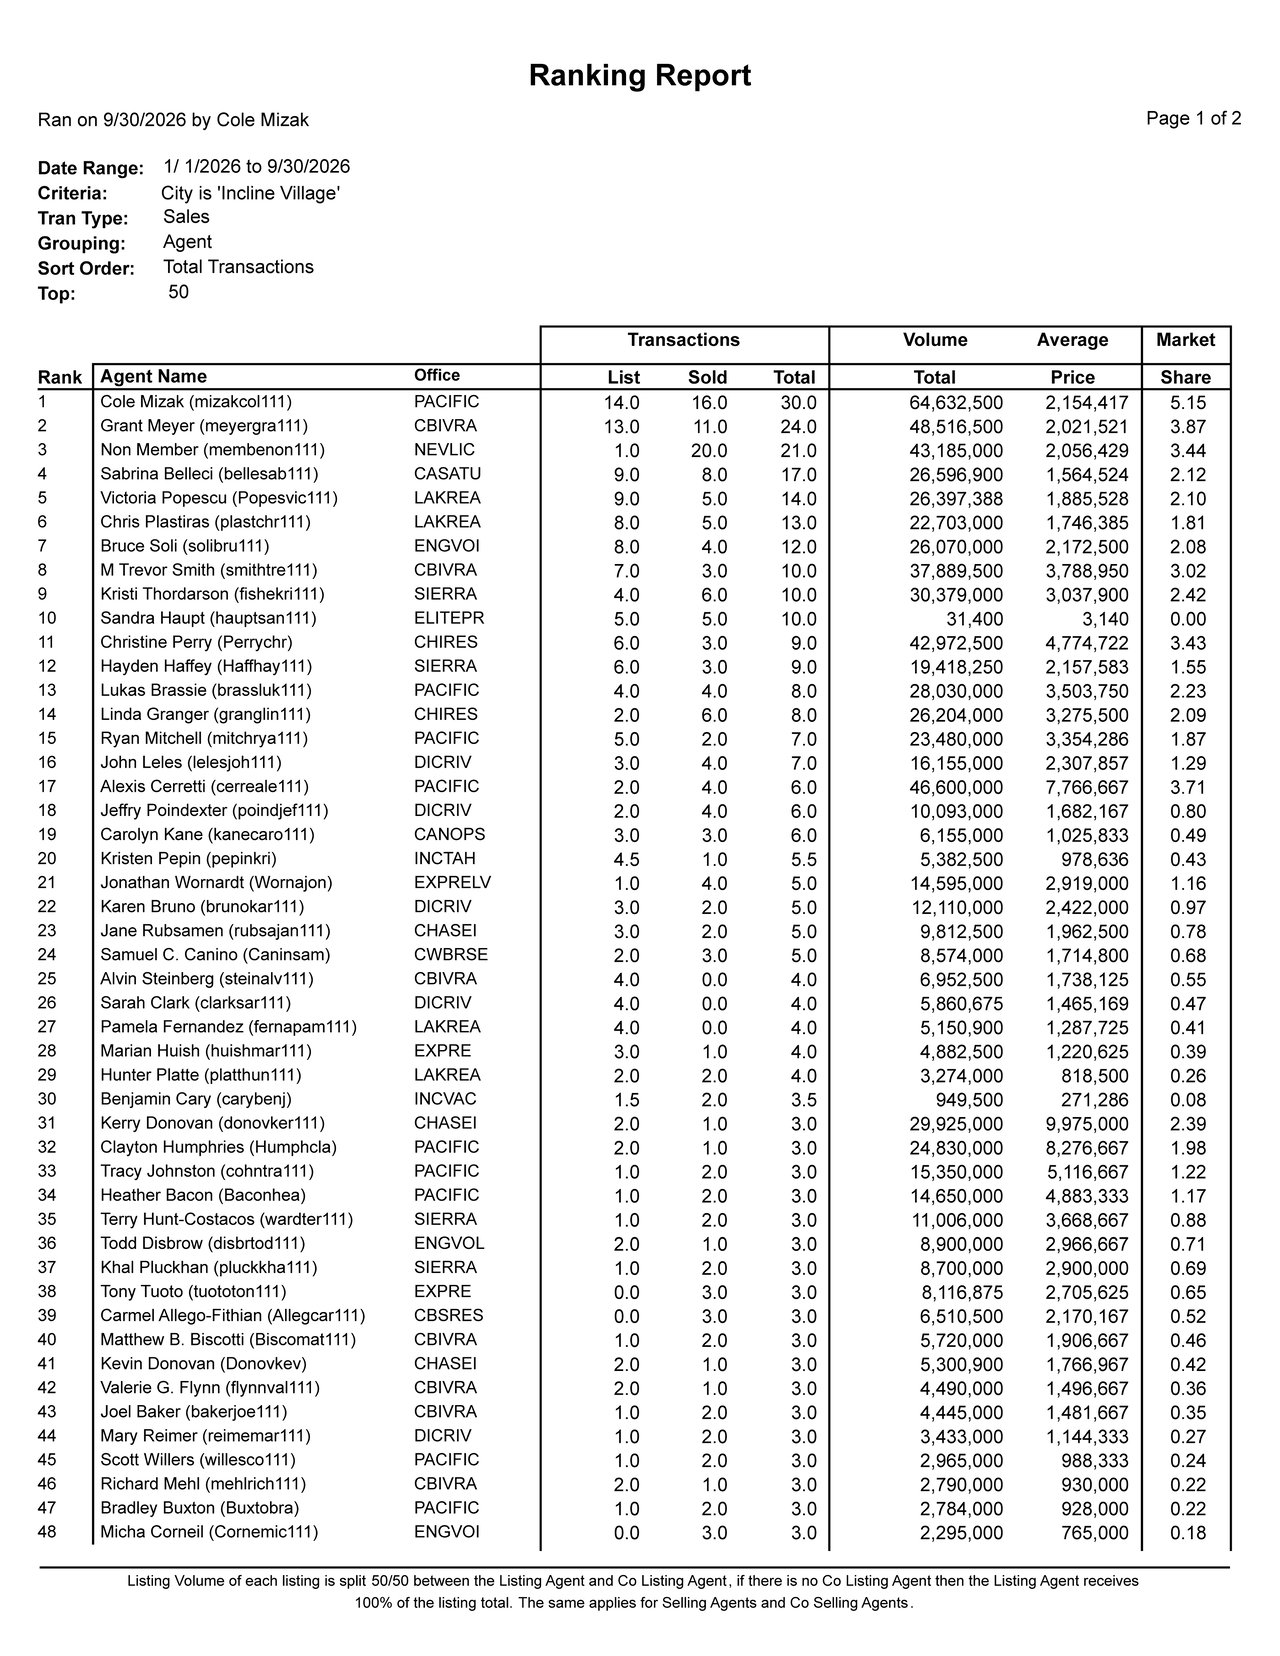
The official IVR MLS rankings are in — who leads Incline Village through three quarters, and what the data means for buyers and sellers.
Lake Tahoe
September 18, 2026
Effective October 15, 2026 — but the statewide average hides who really pays. Here's what it means on each side of the lake.
Lake Tahoe
September 17, 2026
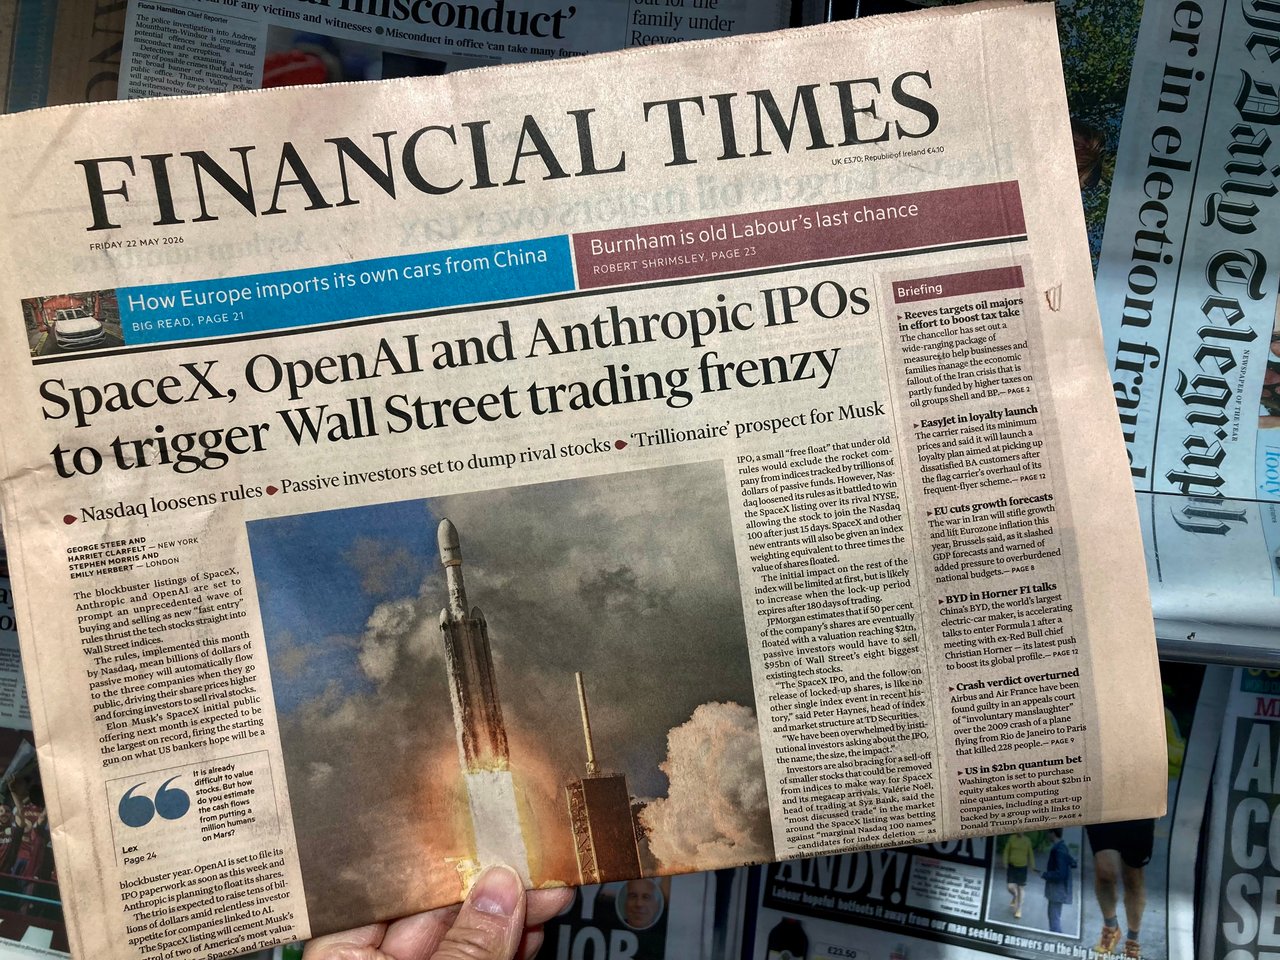
Where you live when you sell can be worth millions — but an IPO windfall isn't taxed the way most people think. Here's what a move can and can't do.
Lake Tahoe
September 15, 2026
Incline's most walkable, family-friendly single-family neighborhood — and its top spot for teardown-and-rebuild.
Lake Tahoe
September 8, 2026
Trophy estates from $10M to a $125M record — and why, on this street, value is measured in feet of frontage, not square feet.
Cole’s mission is to elevate the real estate experience for his clients. He is a long-time Lake Tahoe local and luxury home expert who has developed innovative strategies to provide his clients with an unmatched, bespoke level of service, attention, and support.